US Parmesan Output Jumps 25.9% While Cheddar Slips: Italian Cheese Takes Four In Five Pounds Of Growth
USDA figures published on 5 October show US Parmesan output up 25.9% in August while cheddar fell 0.9%. Italian types have supplied nearly four in every five pounds of US cheese growth so far in 2026.
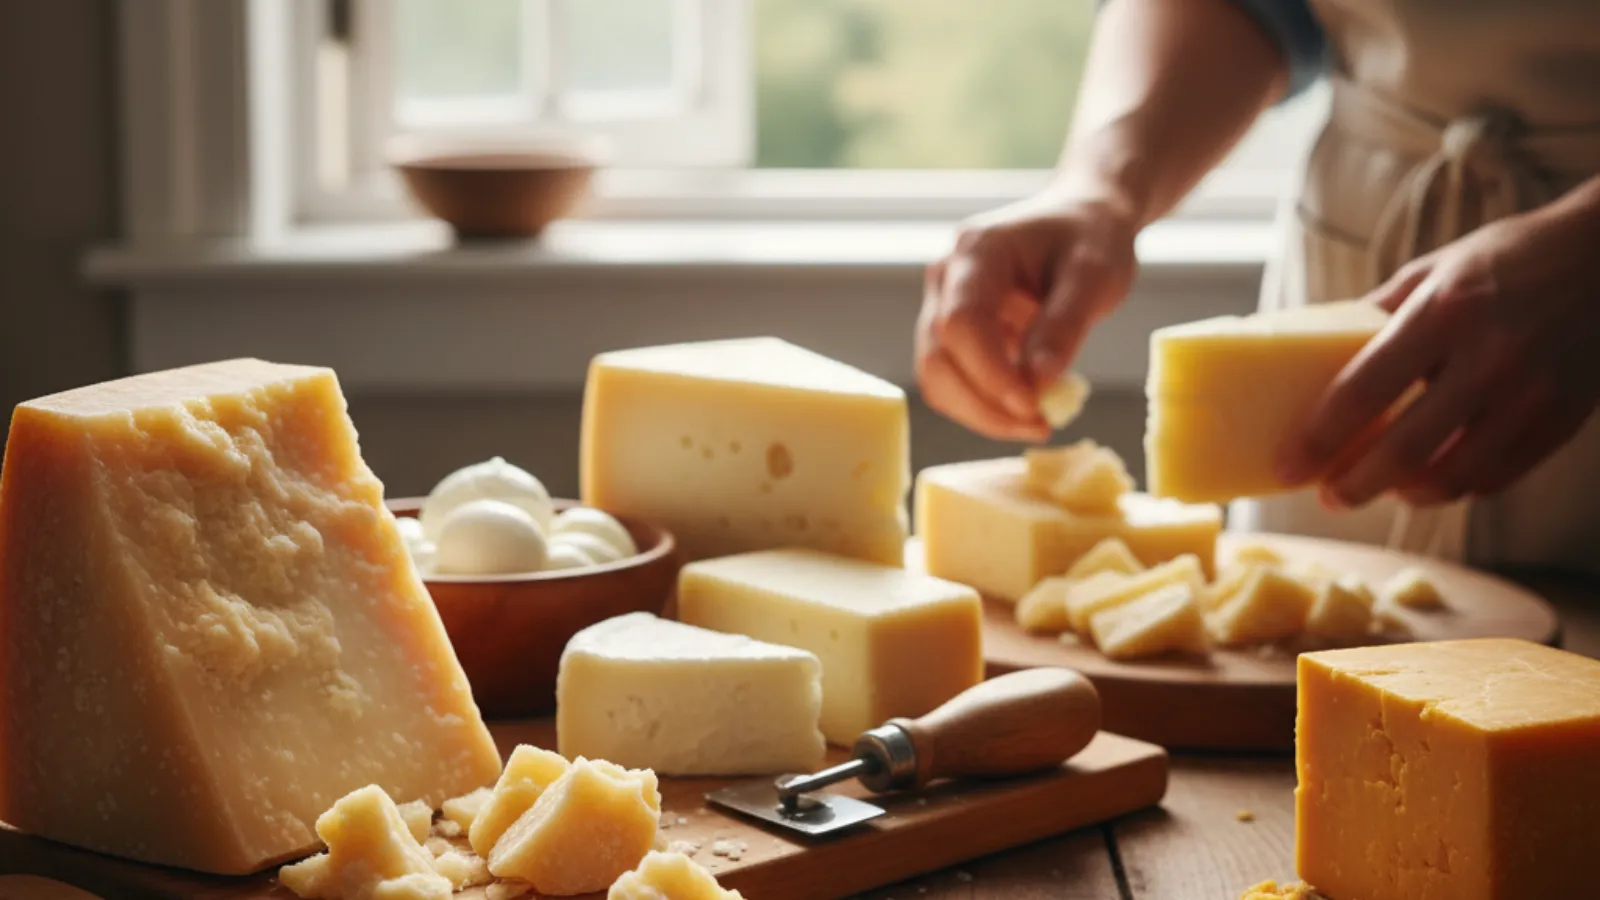
Most of the coverage reads the August cheese print as growth. I read it as a change in which cheese. Parmesan rose 25.9% in the month while cheddar fell.
The August print, type by type
The USDA published its monthly dairy output figures on 5 October. US cheese output in August came to 1.245 billion pounds, or about 565,000 tonnes. That is 1.4% above August last year. Italian types rose 3.7% to 541.3 million pounds while American types fell 0.9% to 477.0 million. Cheddar alone fell 0.9% to 325.9 million pounds. Mozzarella rose 1.8% to 420.9 million. Parmesan rose 25.9% to 52.8 million pounds, about 23,950 tonnes.
Parmesan has run hot for three months
One month proves nothing. Three do. Parmesan output rose 12.2% in June, 25.3% in July and 25.9% in August. In August alone it added about 10.9 million pounds against the same month last year. Provolone turned up too, by 5.3% after a weak July. Ricotta was flat at 20.5 million pounds. The lift sits in the hard grating cheeses rather than across Italian types as a whole. Gouda rose 3.3% and Swiss 1.9%, both from small bases.
Where eight months of growth actually went
The eight-month table is where the shape shows. US cheese output ran to 10.00 billion pounds from January to August, up 2.3%. That is about 4.54 million tonnes. Italian types reached 4.34 billion pounds, up 4.2%. American types came in at 3.87 billion, down 0.1%. Cheddar was down 0.2% at 2.68 billion. Italian types supplied about 79,000 of the 102,000 tonnes added. That is close to four pounds in every five.
American types have stopped growing
Cheddar and the American block types have gone sideways for eight months. That matters because this is where much of the money has gone. The International Dairy Foods Association now counts 14.4 billion dollars across 77 projects in 21 states. Michael Dykes, who leads the body, gave that count on 2 October. He also said cheese and butter are in oversupply. So the spending and the growth are pointing at different cheeses.
What is pulling the hard Italian cheeses
Two forces are worth separating. The first is price at the border. EU food sent to the United States has paid a 15% duty since the 2025 framework. Parmigiano Reggiano and Grana Padano are both caught. A US grating cheese made at home does not pay it. The second is foodservice demand for grated and shredded cheese, which runs on pizza and pasta. Dry whey output rose 8.2% in August. Hard Italian vats throw a lot of whey, so the two move together.
The mix shift reaches well beyond the United States. Italy, Argentina and Australia all run hard-cheese vats aimed at the same grating demand. Fonterra has put capacity into frozen mozzarella for pizza buyers in Asia. Each of those trades carries its own milk price and its own set of buyers. A maker that can sell into two of them has a far easier year. Freight and shelf life also differ by type. A hard cheese travels cheaply and keeps for months, so it can chase demand a long way from the vat. Fresh and soft types cannot, which is why they stay close to the milk.
What this means for the market
A national cheese number is the wrong unit for an entry call. The US table grew 2.3% and its biggest type shrank. Market appeal here belongs to hard Italian cheese and to the kitchens that grate it. Position in the market has moved with it. Makers set up for 40 pound cheddar blocks are chasing a flat pool. Those with grating and shredding lines are not. Any entrant should price the cheese type before the country. Ask which types are actually growing and who holds them. Then ask what a buyer pays to switch.
We will be watching whether hard Italian cheese keeps taking the growth into 2027. The same split is showing up in other large markets. A single national figure hides it completely. Our Global Cheese Database 2026 splits each market into 39 cheese types. It carries output, imports, exports and demand in tonnes. The count runs to 48 countries, with 2025 actuals and forecasts to 2030. The waitlist carries a free sample country chapter.
Global Aseptic Packaging Market Report 2026
148.4bn litres and 344bn packs in 2025. Aseptic volumes across dairy, dairy alternatives, beverages and food in 39 markets — 2025 actuals and forecasts to 2030. Buy online and receive it within 24 hours.
More information
Global Cheese Database 2026
Production, imports, exports and consumption for 39 cheese types across 48 countries, with actuals through 2025 and forecasts to 2030. Join the waitlist for early access, pre-launch pricing and a free sample country chapter.
Get early accessStrategic Insights
📊 Analytics & Strategic Insight
The United States is making more cheese and less of the cheese it is known for
The decision most in this industry are avoiding:
👉 A national output figure is the wrong instrument. Most reading of this release stops at the headline percent. The type table is where the money sits.
👉 Cheddar capacity is being added into a flat pool. Eight months of American-type output have gone nowhere. The spending has not slowed.
👉 A gain of a quarter has a named cause somewhere. Parmesan does not grow 25.9% on shopper whim. Someone commissioned vats and signed buyers.
Here's the full context:
→ 2024: New US cheese plant announcements start landing in volume. Export demand is the stated reason.
→ August 2025: EU food sent to the United States begins paying a 15% duty. Parmigiano Reggiano is caught.
→ June 2026: Parmesan output rises 12.2% on the year. Italian types as a group are still flat.
→ 2 October 2026: The dairy foods body counts 14.4 billion dollars across 77 projects in 21 states.
→ Most recent: Parmesan rose 25.9% in August. Cheddar fell 0.9% in the same month.
What this means for cheese producers, traders and buyers:
✅ Hard Italian cheese is where the US growth is. Grating and shredding buyers are pulling it. The duty on EU hard cheese helps.
✅ A cheddar seller is bidding for a pool that has not grown since January. Share has to come off somebody else.
✅ Whey follows the vat a maker chooses. Dry whey output rose 8.2% in August. Hard Italian cheese makes plenty of it.
What this means for market decisions:
1️⃣ Market appeal has moved to one slice of the table. The country grew 2.3% and its largest type did not.
2️⃣ Plants with grating and shredding lines hold the better position. Block cheddar sites are chasing a flat pool.
3️⃣ An entrant should test the cheese type before the country. Find which types grow in the target market, and who holds them today.
The Zenith view:
A 2.3% national gain proves that US cheese output is rising. It does not prove that the cheese a producer plans to sell is rising with it. Two things decide an investment here. Which of the 39 cheese types holds the growth, and who already owns that pool.
The data behind this story
🧀 Global Cheese Database 2026
Production, imports, exports and consumption for 39 cheese types across 48 countries, in tonnes, with actuals to 2025 and forecasts to 2030. The 2026 edition is being built market by market. Waitlist members get the pre-launch price and a free sample country chapter.
→ Join the waitlist
Evaluating a cheese market or a cheese type? Zenith helps food and beverage companies assess market size, growth, competitors, pricing and route to market before they invest.
→ Discuss your market
Zenith Consulting
Submit your food & beverage project enquiry.
Share your requirements. If there is a strong fit, we’ll come back with an indicative investment range, project timeline and recommended strategic approach.
Reviewed by Zenith Consulting’s senior food & beverage strategy team.
Related analyses
- Corporate Strategy & Portfolio
Oji Liquid Pak's USD 110 Million Vietnam Aseptic Carton Plant Adds 8 Billion Packs To A Region Already At 62 Billion
Oji Liquid Pak broke ground on a USD 110 million aseptic carton material plant in Dong Nai, rated at up to 8 billion packs a year from 2028. Zenith puts Vietnam at 10,358.7 million aseptic packs in 2025, and South East Asia already holds about 62 billion packs of documented converting capacity.
Read analysis → - Corporate Strategy & Portfolio
Spain Swaps HDPE Milk Bottles For Aseptic PET: 170 Million Litres Left And Only Three Aseptic PET Dairy Lines
Spanish UHT milk in large HDPE bottles fell from 307 million litres in 2020 to 170 million in 2025, and Zenith's model takes it to 88.5 million by 2030. Aseptic PET is taking the volume, and only three aseptic PET dairy lines have been documented in the country.
Read analysis → - Corporate Strategy & Portfolio
China Lists All Five Cheese Tariff Codes For US Imports While EU Cheese Pays Up To 11.7%
China has put all five cheese tariff codes on its list of US goods for lower duty, published with the new US-China Board of Trade on 27 September. EU cheese entering the same market pays anti-subsidy duty of up to 11.7%, and New Zealand still holds 61% of the tonnage.
Read analysis →
Share it with your peers
Pass this analysis to colleagues who track the food and beverage market.
Zenith Market Intel
Need a specific food or beverage market report?
Tell us which category, region or question would be useful for your team.
Sister Publication
Also follow our Water Dispense Market Intelligence
Category analyses, operator briefings, and investor signals across the global water dispense market.