Cheddar Jumps 16.5% While Mozzarella Falls 6%: The GDT Cheese Spread Swung $824 A Tonne In Two Weeks
Cheddar rose 16.5% and mozzarella fell 6.0% at the same Global Dairy Trade auction on 15 September. Two cheeses made from the same milk moved $824 a tonne apart in a fortnight, and the reason sits in the vats.
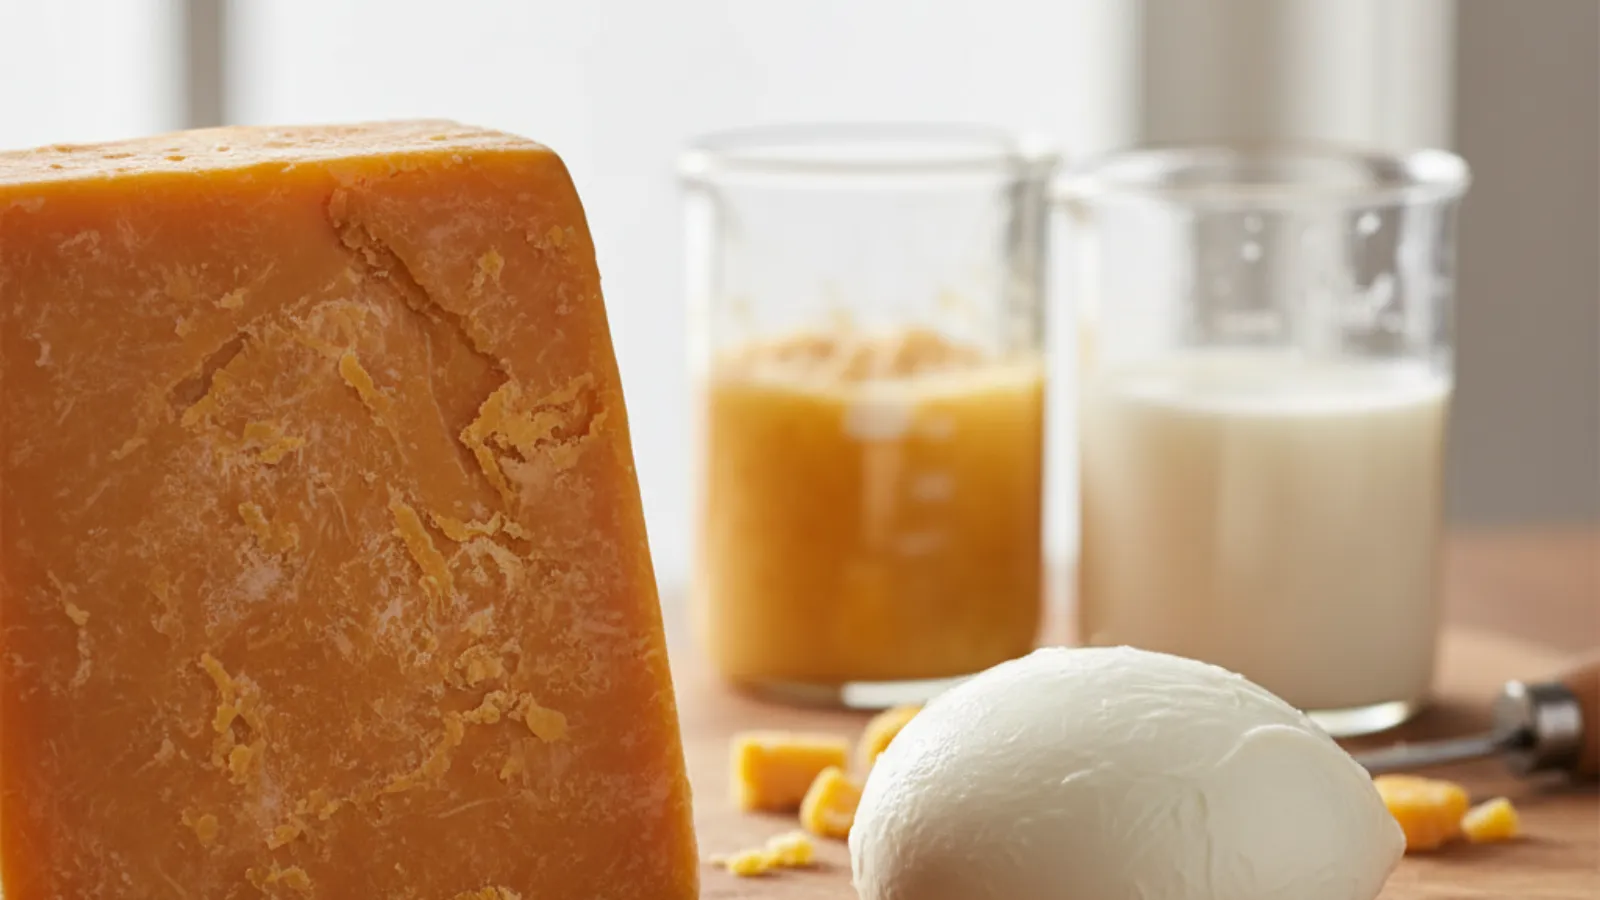
If I were buying cheese this quarter, I would reprice one line today and leave the rest alone. The cheddar line. On 15 September the Global Dairy Trade auction lifted cheddar 16.5% to $4,075 a tonne. Mozzarella fell 6.0% to $3,992 at the same sale.
Two cheeses, one auction, opposite ways
The sale drew 155 bidders, and 126 of them won product. The overall price index slipped 1.1%. That was its first fall since the opening auction in July. Inside that small move, two cheeses went different ways. Cheddar was the only product on the platform to post a double-digit rise. Butter fell 5.7%, anhydrous milkfat 3.0% and whole milk powder 0.8%. Skim milk powder was flat at $3,689 a tonne. Cheddar and mozzarella are the two cheeses listed at these sales. Traders, bakers and food makers across Asia and the Middle East buy both in bulk. A move in either one carries straight into landed cost.
The spread swung 824 dollars a tonne in a fortnight
Two weeks earlier the picture was reversed. At the 1 September sale cheddar fell 6.6% to $3,503 a tonne. Mozzarella rose 0.3% to $4,244 and sat $741 a tonne above it. By 15 September cheddar sat $83 a tonne above mozzarella. The gap between the two moved $824 a tonne in one fortnight. Both cheeses start as the same milk and sell at the same event.
The move runs all the way to February 2027
A short-term squeeze shows up in one contract. This one showed up in five. The October cheddar contract rose 23.7% to $3,940 a tonne, and the February 2027 contract rose 15.7% to $4,155. November gained 20.3% and December 15.4%. Buyers were paying up for cheddar five months out. Mozzarella fell by about 6% across each of its three contracts.
America makes more cheese every year and less cheddar
The supply side explains more here than the demand side. US cheese output in July reached 1.26 billion pounds, up 2.1% on July 2025. Output across the first seven months reached 8.75 billion pounds, up 2.4%. Cheddar output over those same seven months fell 0.1%. July cheddar fell 1.7% to 328.6 million pounds. Mozzarella rose 2.9% in July and 2.4% across the seven months. Italian types took the growth. Their July output reached 551.1 million pounds, up 4.1%. American types fell 1.1% to 479.8 million pounds in the same month. US cheese imports rose 17% in July as well.
The vats changed product rather than closing
Wisconsin shows the shift most clearly. The state made 308.9 million pounds of cheese in July, up 2.4%. Its American-type output fell 8.0% in the same month. Italian types there rose 5.2%. Across the country parmesan rose 25.3% and gouda 30.4%, while cheddar and provolone fell. Foremost Farms leaves 40 pound block cheddar at Marshfield in December. Prairie Farms is closing two cheese plants at Shullsburg. The milk keeps arriving. It goes into a different cheese.
Whey is long while cheddar is short
The side stream tells the same story from the other end. US dry whey output rose 18.7% in July to 78.7 million pounds. Stocks of dry whey ended July 37.4% above a year earlier. Cheddar and mozzarella both yield sweet whey. So a country can grow its whey pool while its cheddar pool shrinks, which is what the July figures show. A cheddar maker earns less from the side stream just as the cheese itself gets dearer.
Four things follow for the rest of 2026. Reprice any uncovered cheddar tonnage before the next auction. Ask whether your supplier can move a vat between cheddar and Italian types, because most cannot. Treat mozzarella as the cheaper cover of the two this quarter. Read the USDA forecast beside the auction. Washington trimmed its 2026 cheese price to $1.5700 a pound on 11 September. Those two numbers now point different ways.
We will be watching whether the cheddar tonnage comes back. A price gap this wide usually pulls product toward it inside two quarters. The answer sits in how much cheddar each country can make. That split by cheese type, market by market, is what our Global Cheese Database 2026 is built to show. The waitlist includes a free sample country chapter.
Global Aseptic Packaging Market Report 2026
148.4bn litres and 344bn packs in 2025. Aseptic volumes across dairy, dairy alternatives, beverages and food in 39 markets — 2025 actuals and forecasts to 2030. Buy online and receive it within 24 hours.
More information
Global Cheese Database 2026
Production, imports, exports and consumption for 39 cheese types across 48 countries, with actuals through 2025 and forecasts to 2030. Join the waitlist for early access, pre-launch pricing and a free sample country chapter.
Get early accessStrategic Insights
📊 Analytics & Strategic Insight
Cheddar has become the thinnest cheese in the world supply base
The decision most in this industry are avoiding:
👉 Cheese cover is still bought as one line. Most buying teams hold a cheese budget rather than a cheddar budget and a mozzarella budget. The two just moved $824 a tonne apart.
👉 Vat flexibility was traded away for yield. Plants that specialised into one cheese type won on cost. They gave up the ability to follow a price.
👉 The side stream falls as the cheese rises. Dry whey stocks are 37.4% higher than a year ago. A cheddar maker cannot count on the whey credit to carry a weak month.
Here's the full context:
→ 2025: US cheese output hit a record, and cheddar grew slower than the Italian types.
→ July 2026: US cheddar output fell 1.7% while total cheese rose 2.1%.
→ August 2026: Foremost Farms said it would leave 40 pound block cheddar at Marshfield.
→ 1 September 2026: Cheddar fell 6.6% at the auction while mozzarella held at $4,244 a tonne.
→ Most recent: Cheddar jumped 16.5% on 15 September. Mozzarella fell 6.0% at the same sale.
What this means for cheese producers, traders and buyers:
✅ Cheddar now prices like a short product. The whole curve moved out to February 2027, so this reads as supply rather than a shipping delay.
✅ Mozzarella is the cheaper cover this quarter. Its pool is still growing at over 2% a year in the United States.
✅ Switching cost is the real asset. A plant that can move a vat between cheddar and Italian types just earned a large option.
3 moves you can make this week:
1️⃣ Split the cheese line in your budget. Give cheddar and mozzarella their own price assumptions for the fourth quarter.
2️⃣ Ask your supplier one question. How many days would it take to move a vat from cheddar to Italian types?
3️⃣ Pull three years of cheddar tonnage by country. Find where the cheddar pool is still growing before the next sale.
The data behind this story
🧀 Global Cheese Database 2026
Production, imports, exports and consumption for 39 cheese types across 48 countries, in tonnes, with actuals to 2025 and forecasts to 2030. The 2026 edition is being built market by market. Waitlist members get the pre-launch price and a free sample country chapter.
→ Join the waitlist
Zenith Consulting
Submit your food & beverage project enquiry.
Share your requirements. If there is a strong fit, we’ll come back with an indicative investment range, project timeline and recommended strategic approach.
Reviewed by Zenith Consulting’s senior food & beverage strategy team.
Related analyses
- Corporate Strategy & Portfolio
SIG Backs India's Regional Drinks: Aseptic Filling Has Fallen To 40.3% Of Indian Ambient Beverage Volume
SIG argues that aseptic cartons can take India's regional drinks national. Zenith's India data shows aseptic filling losing 17 points of ambient beverage share since 2020, while UHT milk grows at 12.3% a year.
Read analysis → - Corporate Strategy & Portfolio
China Aseptic Packaging: Litres Keep Rising, Packs Have Stopped, And The Average Pack Is Now 343ml
China filled 37,391 million litres of aseptic product in 2025 and used no more packs than it did in 2020. Zenith's Global Aseptic Packaging Market Report 2026 shows why the litre line and the pack line have split.
Read analysis → - Corporate Strategy & Portfolio
Aseptic Filling Still Trails Hot Fill In 2030: Zenith Puts The Gap At 946 Million Litres
Zenith's Global Aseptic Packaging Market Report 2026 puts aseptic filling at 38.9% of the world's ambient long-life drinks against 42.6% for hot filling. By 2030 the gap narrows to 946 million litres, and the fastest-growing route of all is the cheapest one.
Read analysis →
Share it with your peers
Pass this analysis to colleagues who track the food and beverage market.
Zenith Market Intel
Need a specific food or beverage market report?
Tell us which category, region or question would be useful for your team.
Sister Publication
Also follow our Water Dispense Market Intelligence
Category analyses, operator briefings, and investor signals across the global water dispense market.